


Price Snapshot - September 18 Close
| Benchmark | Latest | Week Change | Reading for Buyers |
|---|---|---|---|
| LME copper 3M | $14,562/t | +2.26% WoW | Dip mostly recovered; new 2026 high territory |
| LME aluminium 3M | $3,300/t | +1.44% WoW | Net positive over two weeks; floor intact |
| LME zinc 3M | $3,940.5/t | +1.53% WoW | Plating cost relief reversed |
| LME nickel 3M | $16,235/t | −1.42% WoW | Only base metal still easing |
| SHFE copper front-month | ¥109,530/t | +¥1,420 Friday | Domestic physical premiums firm |
| SHFE aluminium | ¥24,385/t | +0.72% | Ingot destocking accelerating |
| SHFE stainless (2611) | ¥13,690/t | +¥120 | Firming with nickel complex mixed |
| Hot-rolled coil (2701) | ¥3,302/t | −¥25 | The only soft complex - see below |
| LME copper stocks | 255,900 t | +9.0% WoW | Availability recovering, price rising anyway |
| LME aluminium stocks | 242,600 t | −0.7% WoW | Still near multi-decade lows |
| USD/CNY (onshore close) | 6.6973 | RMB +123 pips WoW | Strongest level this year - FX headwind on USD quotes |
Exchange settlement data, week of September 15–19, 2026. SHFE front-month unless noted.
The Ten-Day Round Trip
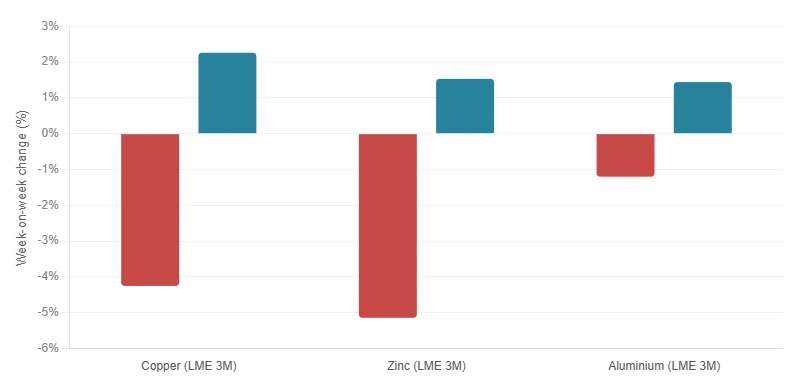
Week-on-week percentage change on the London benchmark: week of Sep 8–12 versus week of Sep 15–19, 2026.
Read the chart as a round trip, not as two separate moves. Copper gave up 4.25% on the stalled-tariff unwind, then took 2.26% of it straight back on improving Chinese physical demand. Zinc fell 5.14% and recovered 1.53%. The buyers who moved inside the ten-day window captured the only genuine metal-cost relief this quarter. The buyers who waited for "the trend to confirm" are now looking at a higher copper price than the one they hesitated on.
The more important line is aluminium. Its two-week net change is positive: down 1.2% on the crash week, up 1.44% this week. Aluminium never really corrected, because it never carried a policy premium to unwind - only a physical scarcity, and that scarcity is intact: London stocks sit at 242,600 t, still close to multi-decade lows, Shanghai ingot destocking is accelerating, and the cash-to-three-month spread remains in backwardation. For shops pricing aluminium parts, the metal line in the quote is not going to give anything back. The processing fee is still the only negotiable line, and that remains true this week.
The Demand Data That Changed the Argument
What makes this week different from every prior week of the rally is that the demand side of the equation is no longer an assumption. The August factory data released this week shows the machined-parts economy accelerating:

August 2026 year-on-year output growth by segment, plus fixed-asset investment (Jan–Aug). Official statistics released September 15, 2026.
Your downstream is expanding faster than the economy. Industrial value-added grew 5.2% year-on-year in August, accelerating 0.7 points from July. But the segments that buy machined components grew two to three times faster: equipment manufacturing +12.1%, high-tech manufacturing +16.7%, industrial robot output +34.6%, lithium battery output +57.2%, 3D printing equipment +29.9%. If your parts go into automation, energy or precision equipment, your end-market is in a boom, not a slowdown.
Producer prices are accelerating, which green-lights pass-through. The factory-gate index rose 3.8% year-on-year in August, widening for another month. Combined with accelerating output, this is the textbook configuration in which suppliers start marking up rather than absorbing. The two-to-four-quarter lag between input costs and machine-shop quotes has been the recurring theme of this series; the current price environment says that lag is now working against buyers, not for them.
The profit and export numbers close the loop. Industrial profits for the first seven months of the year were up 17.6% year-on-year - meaning the factories absorbing higher input costs have margin room to keep ordering rather than destocking. Goods trade grew 19.8% in August alone, on top of the record machinery-and-electronics exports already logged earlier this quarter. The demand behind this week's metal recovery is export- and equipment-driven, which is precisely the demand base a machine shop serves.
The exception is construction-linked demand, and it is shrinking. Fixed-asset investment fell 7.2% in the first eight months. The two-speed economy is real and it is widening: advanced manufacturing expands while construction-linked categories contract. For buyers this cuts both ways - shops serving the booming segments (robotics, batteries, precision equipment) will be less flexible on price and lead time than shops still waiting for construction-linked orders to return. Know which type of shop is quoting you.
The counter-signal worth understanding. London copper inventories rose 9.0% this week to 255,900 tonnes - the steepest increase of any base metal - and the price rose anyway. That combination rules out a scarcity-driven rally: this is a demand-driven recovery in which delivered metal is being absorbed by physical buyers faster than it arrives. For procurement, demand-driven rallies are the harder kind to wait out, because they end when order books are filled, not when a position is unwound. There is no policy announcement coming that hands you back the September 10 prices.
Steel Is Now the Only Soft Complex - and That Is an Opportunity
While copper, zinc and aluminium all rose this week, ferrous went the other way - and the reason is one machined-part buyers can work with. Hot-rolled coil settled at ¥3,302/t with mill margins decisively negative: benchmark rebar losses around ¥218/t and hot-rolled coil losses around ¥69/t. Losses of that size historically trigger production cuts and maintenance shutdowns within weeks, which builds a floor under the price rather than extending the decline. Stainless, by contrast, firmed with the broader metals complex.
Practical translation: carbon-steel and plate parts are the best negotiation territory in the market right now. Mills are losing money, iron ore is drifting, and steel-service centres want volume. Meanwhile every other material line in your bill of materials is rising. If your assembly mixes steel brackets or housings with aluminium or stainless components, this is the week to push hardest on the steel line items and lock them for Q4 volume before mill cuts tighten the sheet market.
请替换当前内容 This 50kVA single phase pole mounted transformer is exported to Canada inJuly,2024.The rated power of the pole mounted transformer is 50 KVA, the primary voltage is 34.5 kV and secondary voltage is 0.48v/0.277 KV.
请替换当前内容 This 50kVA single phase pole mounted transformer is exported to Canada inJuly,2024.The rated power of the pole mounted transformer is 50 KVA, the primary voltage is 34.5 kV and secondary voltage is 0.48v/0.277 KV.
The Currency Line Nobody Puts in the Quote
Two macro events this week matter for landed cost. First, the offshore funding rate decision landed exactly as expected, so no macro shock is working through the metals complex - the rally is being carried by physical demand, which makes it more durable, not less. Second, the yuan closed the week at 6.6973 to the dollar, its strongest level this year, appreciating 123 pips in five days.
For international buyers, that currency move does real work: a quote set in USD against a strengthening RMB is a quote whose margin is being quietly squeezed on the supplier side. Expect quotes issued in the coming weeks to be either marginally higher in USD or shorter-dated than usual. If you receive a quote with a 30-day validity where you are used to 60 or 90, the exchange rate is the reason. One mitigation is worth raising directly in negotiation: ask for the quote in USD with a re-validation trigger if the pair moves beyond an agreed band - suppliers holding inventory purchased at today's exchange rate will usually accept that structure, because it shares the risk rather than transferring it.
Worth noting on timing: the September reading of the private-sector manufacturing survey lands at the end of this month, and it is the last hard demand datapoint before Q4 contracting season. August's release showed the strongest reading in months with output expanding for nine consecutive months. A second strong print would remove the final "wait and see" argument from any procurement calendar still open on Q4 volumes.
What to Do This Week, by Material
Copper and brass parts: the re-quote window from the September 10 dip has closed. If your quote was never marked down, do not expect it to be now - the metal is back above its pre-dip path. Structure new quotes on copper weight at prevailing spot with a reset clause, so a future correction flows to you automatically.
Zinc-plated and galvanised parts: plating-cost relief lasted exactly one week. Treat any plating-heavy quote built at last week's low as lucky, not repeatable, and re-baseline at current levels.
Aluminium parts: no metal relief is coming; the two-week net move is positive and inventories say it stays that way. Your lever is the processing fee and the batch ladder - both remain negotiable while competition for orders persists.
Carbon steel and plate parts: the soft complex. Push price and lock Q4 volume now, before negative mill margins trigger the production cuts that will build the floor.
Stainless parts: firming with the metals complex; the nickel line is the only easing input. Quote with the same reset-clause logic as copper.
All Q4 volumes: the pass-through window is closing from both ends - materials rising, demand data strong, PPI accelerating. Signing this month prices your Q4 build into the last week before the evidence for markups became overwhelming.
Our Machining Capabilities
| Capability | Specification | Typical Parts |
|---|---|---|
| 3-Axis CNC Milling | Up to 1,050 × 650 × 600 mm Tolerance ±0.01 mm |
Brackets, housings, plates, enclosures |
| 5-Axis CNC Milling | Up to ø600 mm Tolerance ±0.005 mm |
Impellers, structural parts, complex geometry |
| CNC Turning | ø2–300 mm Tolerance ±0.005 mm |
Shafts, fittings, bushings, connectors |
| Swiss-Type Turning | ø0.5–32 mm | Micro precision parts, medical components |
| Wire EDM | ±0.003 mm | Hardened parts, fine slots, tooling |
| Materials | Aluminium 6061/7075, carbon steel 1018/1045, alloy steel 4140, stainless 304/316/17-4PH, titanium Gr2/Gr5, copper, brass, bronze | Material certs (MTR) available |
| Surface Finishing | Anodising (Type II/III), powder coating, bead blasting, polishing, zinc plating, black oxide | RoHS-compliant options |
| Quality & Inspection | CMM dimensional reports, FAI (AS9102), CofC, ISO 9001 system | Full traceability on request |
Price Q4 volumes before pass-through finishes closing
Upload your STEP or IGES files and receive a binding quote with a line-item breakdown that separates material from processing fee, valid against current metal prices and exchange rates - plus free DFM feedback, within 24 hours.


